What happens in the finance and insurance (F&I) office
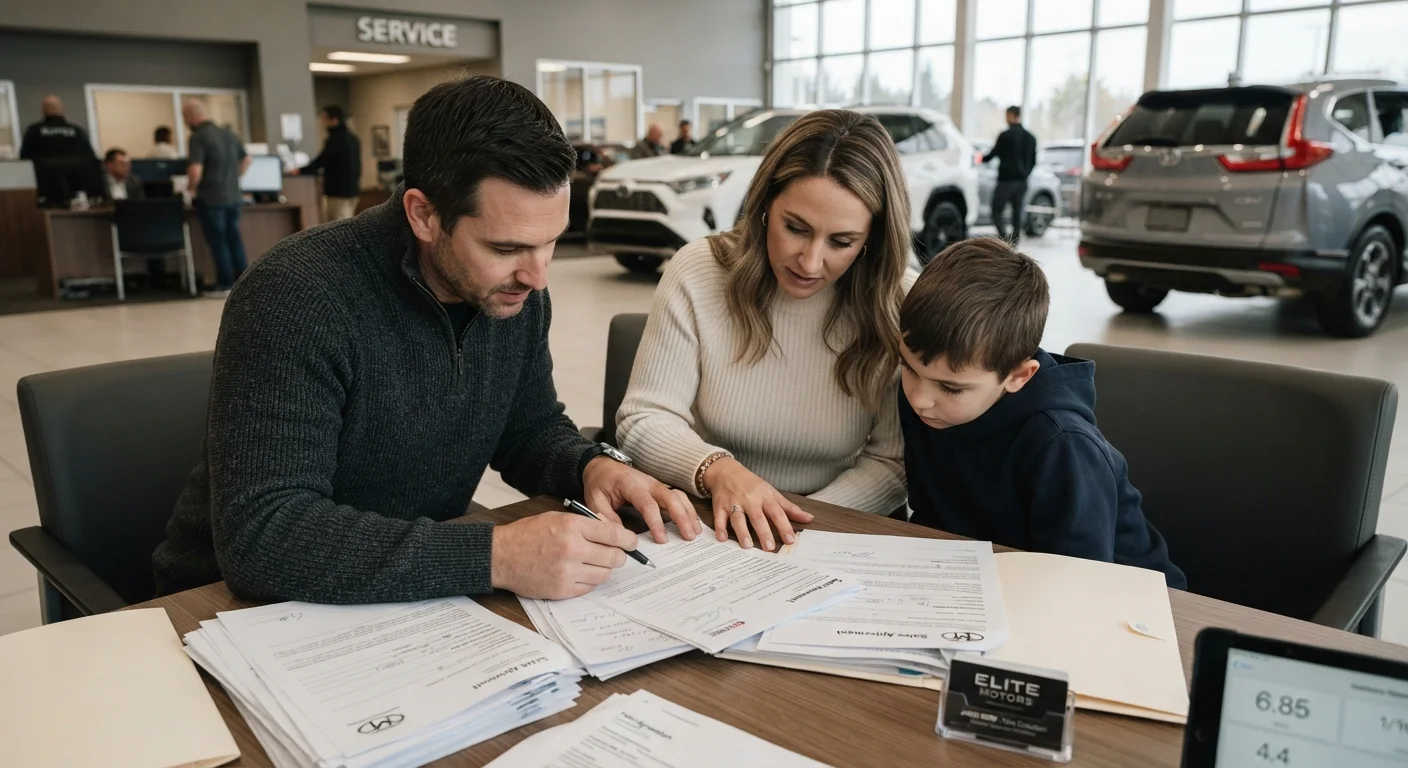
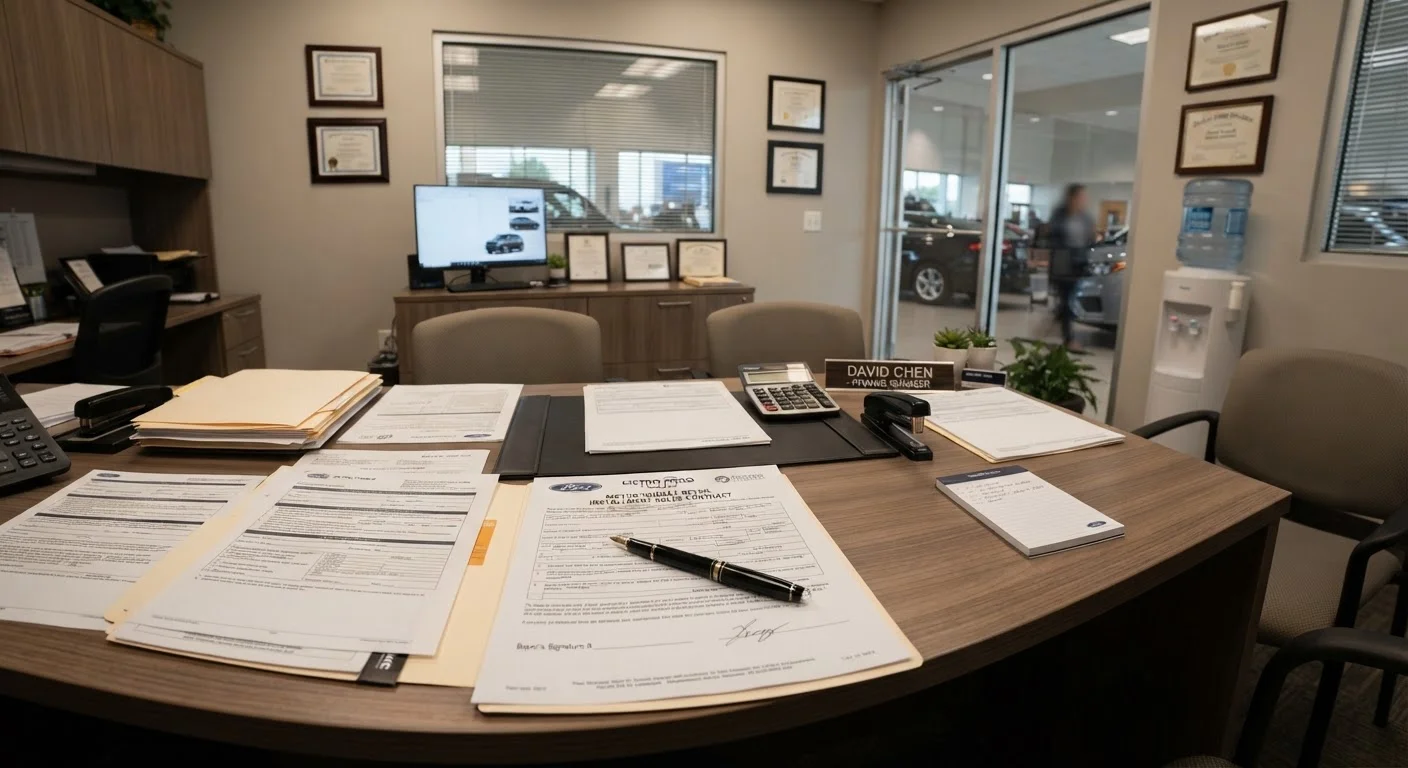
After you agree on a vehicle price, the dealership directs you to the finance and insurance (F&I) office. This is where the financing paperwork is completed and where the F&I manager presents a menu of additional products. These products are optional, though the presentation does not always make that obvious.
Each product carries a price that gets added to your loan balance or paid upfront. Because the cost is folded into a monthly payment, a $1,200 add-on can feel like a small number. Over a 60- or 72-month loan with interest, that product costs more than its sticker price. Understanding how financing affects total cost is worth doing before you reach this room.
F&I office
The finance and insurance office at a dealership where loan paperwork is signed and optional products are offered. F&I managers are paid partly on what products they sell.
GAP coverage
Guaranteed Asset Protection pays the difference between your outstanding loan balance and the actual cash value your insurer pays if the vehicle is totaled or stolen. It is relevant mainly when you owe more than the vehicle is currently worth.
Extended service contract
A paid agreement that covers certain repair costs after the factory warranty expires. Terms, exclusions, and deductibles vary significantly between contracts, so reading the full document is necessary.
Dealer markup
The difference between what a dealership pays for a product and the price charged to the buyer. F&I products typically carry substantial markups, which means there is often room to negotiate.
Powertrain warranty
Coverage limited to the engine, transmission, and drivetrain components. It excludes electronics, air conditioning, and many other systems that an extended contract might or might not cover depending on its terms.
Common add-ons and what they actually cover
Extended service contracts (often called extended warranties) extend mechanical coverage beyond the manufacturer's factory warranty. The terms vary widely: some cover only the powertrain, others cover electronics and labor. Read the exclusions list before agreeing, because that list defines what the product actually does.
GAP coverage (Guaranteed Asset Protection) pays the difference between what you owe on a loan and what your auto insurer pays if the vehicle is totaled or stolen. It matters most when you financed a large percentage of the vehicle's price, since new vehicles depreciate quickly. Your auto insurer may offer GAP at a lower cost than the dealership, so compare before deciding.
Paint and fabric protection packages usually involve a sealant applied at the dealership. The price charged at signing is often much higher than the cost of comparable consumer products available elsewhere. Ask exactly what is being applied and what the warranty covers.
Tire and wheel protection covers repair or replacement costs from road hazards such as potholes. If you drive frequently on rough roads or in areas with harsh winters, this may be worth evaluating. If most of your driving is highway miles on well-maintained roads, it may see little use.
Credit life and credit disability insurance pay your loan if you die or become disabled. These are generally available at lower cost through standalone life or disability insurance policies. Consumer finance guides consistently note that dealership pricing for these products runs high relative to the coverage provided.
How to evaluate each product on its own terms
For any add-on, ask three questions. First, what exactly does it cover and what does it exclude? Get the contract, not a verbal summary. Second, can you buy equivalent coverage elsewhere at lower cost? GAP and extended service contracts are both available through insurance companies and some credit unions. Third, if you add this to your loan, what is the total cost with interest by the time the loan is paid off?
A pre-purchase inspection on a used vehicle can reduce the uncertainty that makes extended service contracts feel necessary. A vehicle with a clean mechanical history and low mileage carries different risk than one with deferred maintenance.
Leased vehicles have different dynamics. Some add-ons are less relevant on a lease because you return the vehicle after a fixed term. See what lease agreements involve for a broader picture of how those terms work.
| Are add-ons required to complete a purchase? | No. Every F&I product is optional. |
| Can GAP be purchased elsewhere? | Yes. Auto insurers and some credit unions offer GAP coverage, often at lower cost. |
| When does GAP matter most? | When you finance a high percentage of the vehicle's price and the loan balance could exceed the car's value early in the loan term. |
| Can you negotiate F&I product prices? | Yes. These products carry dealer markup and prices are not fixed. |
| Can you buy an extended service contract after signing? | Sometimes. Independent warranty providers cover some vehicles after purchase. Check eligibility before assuming the dealership is the only source. |
What you can do before and during signing
Request the F&I product menu in advance. Many dealerships will share it by email if asked. This gives you time to check whether your auto insurer offers GAP, whether an independent warranty company covers the same vehicle, and whether the paint sealant is something the manufacturer already applies at the factory.
You can decline any individual add-on. The purchase contract does not require you to accept all products to proceed. If the F&I manager says otherwise, ask to see where that requirement appears in writing.
If you do want an extended service contract, negotiate the price. These products carry dealer markup, and the F&I manager has room to adjust. Buying the contract later, after the sale, from an independent provider is also an option for some vehicles.
Financing decisions and add-on decisions interact. A higher loan balance from add-ons means more interest paid overall. That connection is easy to overlook when the focus is on a monthly figure rather than the total paid.